

Sofa Finance for Bad Credit in NI: 2026 Buying Guide
Could a poor credit history rule out sofa finance, or is the decision less straightforward? If you’re searching for sofas on finance bad credit NI, it’s understandable to feel unsure about applying and concerned about what a credit check could mean for your file. A past credit problem doesn’t guarantee either approval or rejection: the lender assesses each application.
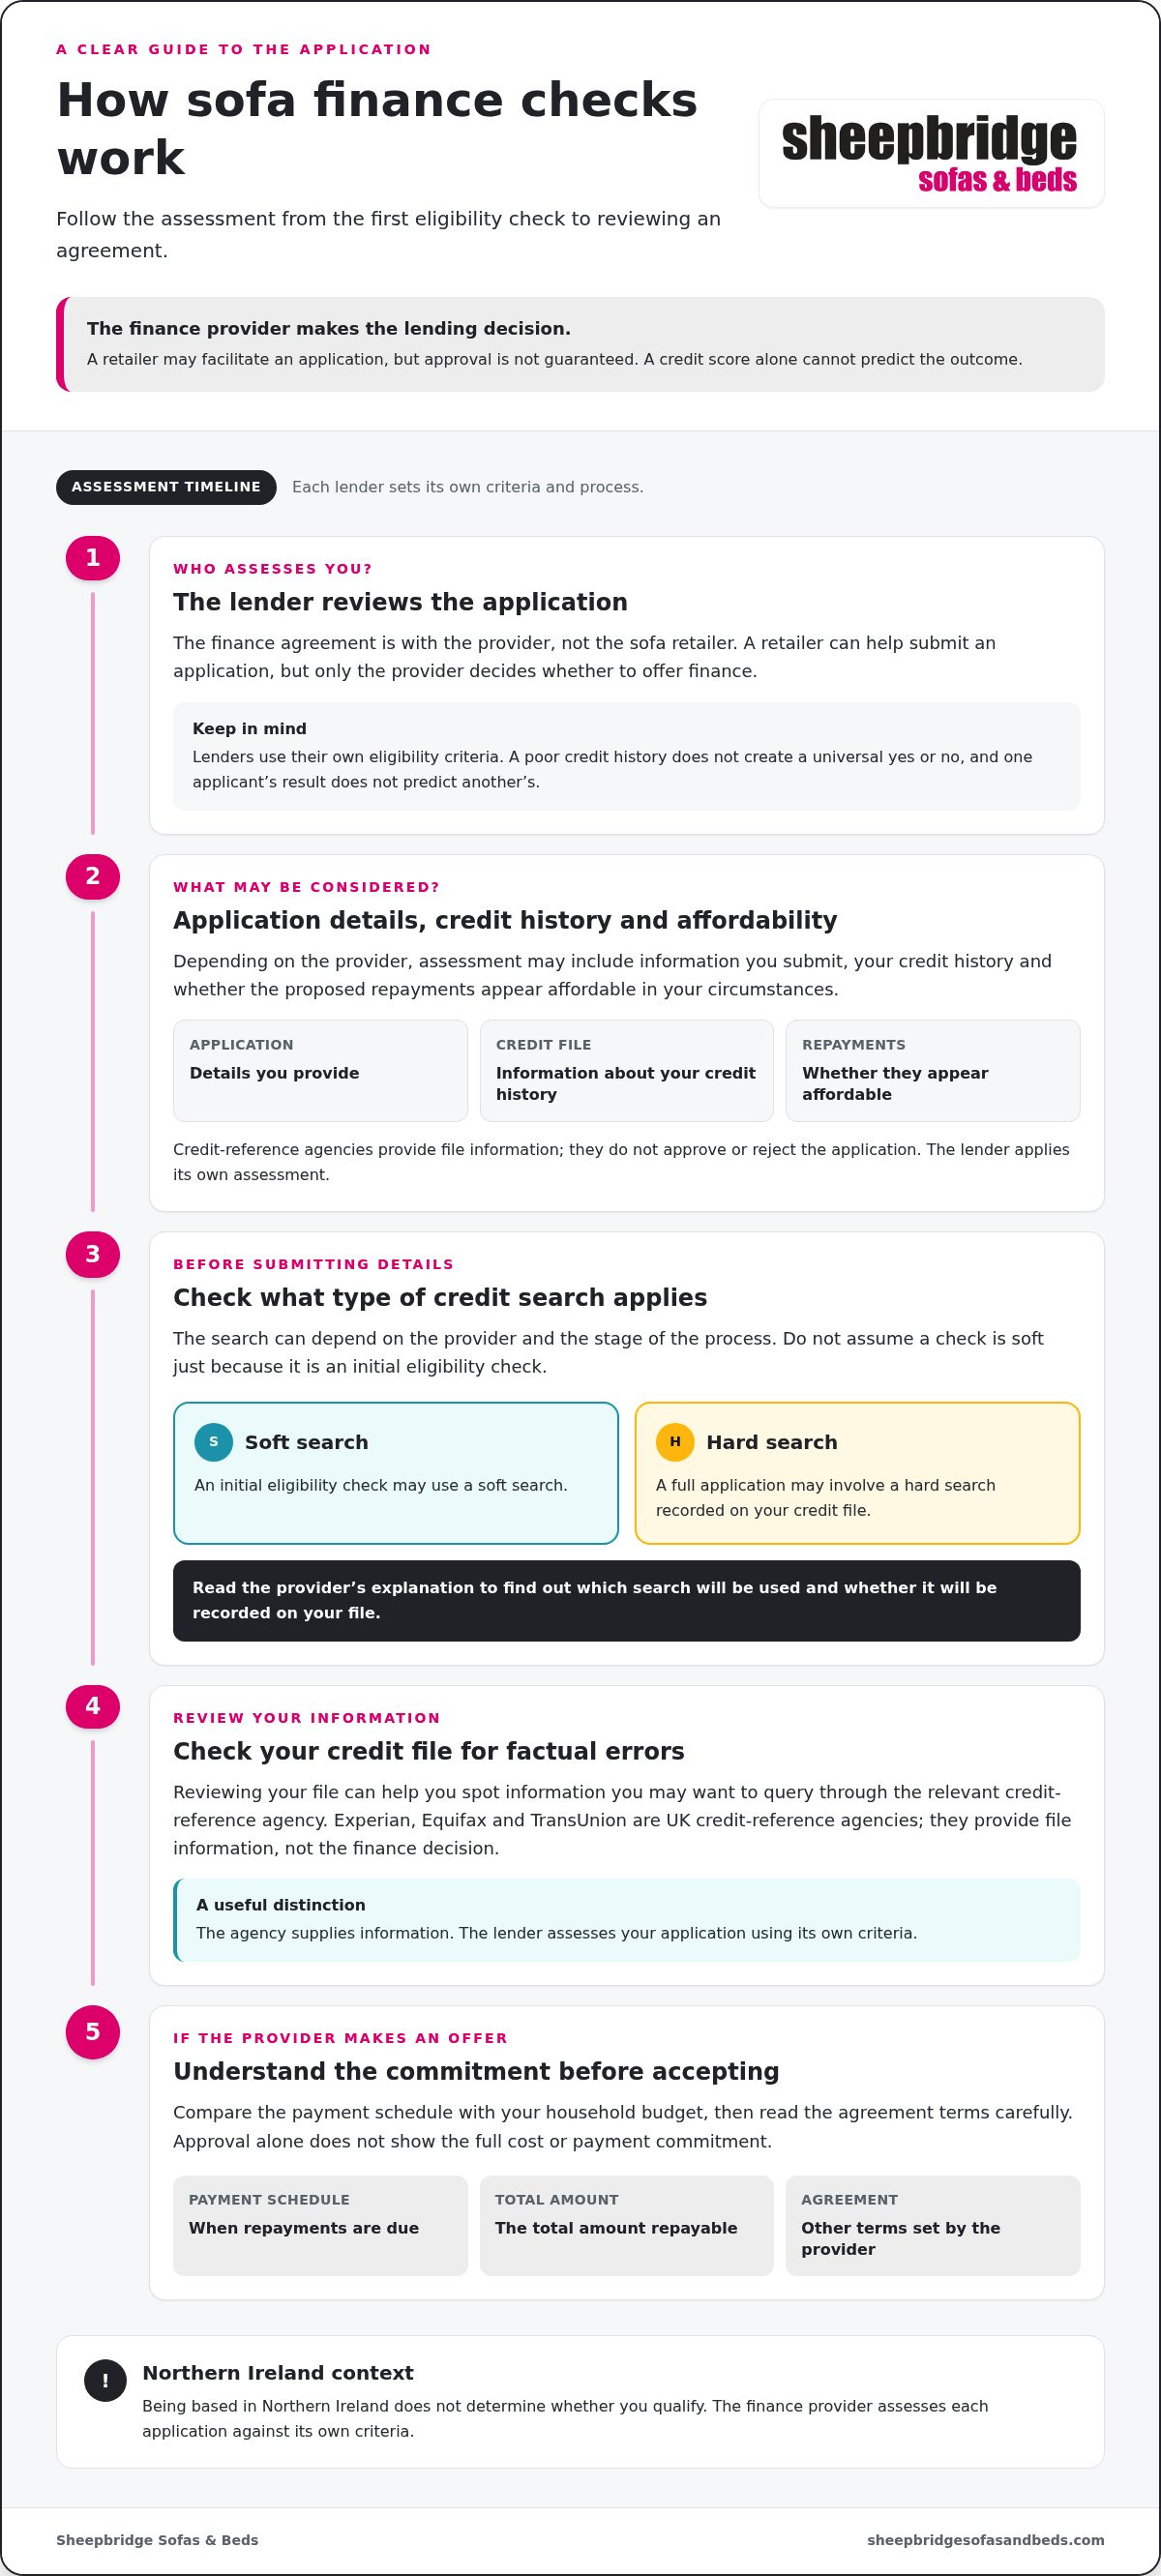
Before taking the next step, understand what an application may involve. An initial eligibility check may use a soft search, while a full application can involve a hard search recorded on your credit file. The process and agreement terms depend on the lender, so read the details before proceeding.
This guide explains how sofa finance applications work, what to review before applying, and how to compare repayments with paying upfront or waiting. It also covers how to weigh the total amount repayable against your household budget. Sheepbridge Sofas & Beds is a family-run Newry retailer, established in 2012, with a range of sofas and free delivery and installation across Northern Ireland.
Key Takeaways
- With sofas on finance bad credit NI, each lender uses its own criteria, so a credit score alone can’t predict the outcome.
- Compare finance with paying upfront or waiting, including how each option fits your budget and future flexibility.
- Before applying, review your household budget, read the lender’s terms and check your credit file for factual errors.
- Explore manual recliners, corner sofas, and fabric or leather suites at Sheepbridge, a family-run Newry retailer established in 2012.
- Understand what to look for in an agreement before deciding whether finance is right for you.
Sofas on finance with bad credit in NI: what applicants should know
Wanting a comfortable new sofa while worrying about your credit history is understandable. Searching for sofas on finance bad credit NI can bring up plenty of uncertainty, but a poor credit record doesn’t create a universal yes or no. Sofa finance is a credit agreement: you borrow towards a purchase and repay under the lender’s agreed terms. Review the payment commitment carefully before applying.
A retailer can facilitate an application as part of buying a sofa, but the finance provider makes the lending decision. The retailer doesn’t decide whether your application meets the lender’s requirements. For background on the UK consumer credit framework, the Consumer Credit Act 1974 provides useful context. For your application, the specific agreement and its terms are what matter.
Does bad credit automatically prevent sofa finance?
No single credit score can tell you exactly what a provider will decide. Lenders set their own eligibility criteria and assess applications using their own processes. A poor credit history is one part of the picture; your current financial circumstances and whether repayments appear affordable may also be considered. One applicant’s outcome doesn’t predict another’s, even if their credit histories seem similar.
A retailer’s help with an application isn’t a promise of acceptance. Only the provider can assess the information and decide whether to offer an agreement. If you’re comparing sofas on finance bad credit NI, treat eligibility information as guidance, not a guarantee, and read the provider’s terms before committing.
In short: approval is never guaranteed and rests with the finance provider.
What does sofa finance mean for a Northern Ireland shopper?
With finance, you enter into an agreement with the provider, not the sofa retailer. The retailer may facilitate the application, while the provider sets the terms and decides whether to lend. If you receive an offer, review the payment schedule, total amount repayable and other terms before accepting. This gives you a clearer picture of the commitment than approval alone.
Northern Ireland is the local shopping context, but being based here doesn’t determine whether you’ll qualify. The provider assesses your application against its own criteria. You can weigh the sofa choice alongside the payment decision. Sheepbridge Sofas & Beds is a family-run Newry retailer with manual recliners, corner sofas, and fabric and leather suites. Its sofas in Newry buying guide offers local context for exploring sofa styles and delivery across Northern Ireland.
How sofa finance applications assess credit and affordability
A finance decision isn’t based on a credit score alone. Providers set their own criteria and may consider your credit history alongside your application details and current ability to manage repayments. That’s why searches for sofas on finance bad credit NI can’t be answered with a prediction based on one score: providers may assess applications differently, and only the lender can decide.
Credit-reference agencies provide information about your credit file, but they don’t approve or reject your sofa finance application. A lender may use agency information as part of its assessment, then apply its own eligibility and affordability processes. Applying through a retailer doesn’t bypass those checks. The retailer can facilitate an application, but the finance provider assesses it.
What information might a finance provider consider?
Depending on the provider, an application may be assessed using information that helps establish your identity, the details you submit, your credit history and whether the proposed repayments appear affordable in light of your circumstances. Criteria vary between lenders, so don’t assume one factor automatically decides the result.
For example, a lender may consider information in your application alongside credit-file details rather than treating a score as the whole story. What it asks you to provide, and how it weighs each detail, depends on its process. Read the provider’s application guidance and terms for the specific requirements. A general checklist won’t tell you exactly what every lender will ask for.
Will applying affect your credit file?
It depends on the type and stage of the check. Some providers describe an initial eligibility check as a soft search, while a formal application may involve a hard search. Don’t assume a search is soft just because you’re checking whether finance might be available. Before submitting details, read the provider’s explanation of the search type and whether it will be recorded on your credit file.
Experian, Equifax and TransUnion are UK credit-reference agencies. They provide credit-file information, but they aren’t the lender making your decision. Naming them doesn’t imply an affiliation with Sheepbridge Sofas & Beds. For local guidance on credit files and credit agreements, nidirect’s information about credit reference agencies in Northern Ireland is a useful reference. Reviewing your file can help you spot information you may want to query through the relevant agency.
Understand the provider’s check before moving ahead. If you’re also weighing up sofa styles, explore sofa options at Sheepbridge Sofas & Beds while considering the finance decision separately.
Compare sofa finance, paying upfront, and waiting to buy
There isn’t one payment route that suits every household. Compare the commitment, when money leaves your budget, and how much flexibility you’ll have if circumstances change. Finance spreads payments over time, but the instalment alone doesn’t show the full cost. Paying upfront avoids a new credit agreement, while waiting gives you time to save or reconsider what you need.
| Option | Commitment | Payment timing | Flexibility if circumstances change |
|---|---|---|---|
| Finance | You agree to repay under the provider’s terms. | Payments are spread according to the agreement. | Repayments remain a commitment. Check the agreement for what applies if you can’t keep up. |
| Pay upfront | No finance agreement for the purchase. | You pay the full amount at purchase. | No finance repayments, but using savings reduces the money available for other needs. |
| Wait to buy | No new payment commitment now. | You can save towards a future purchase. | You retain more choice about timing, though your needs or available sofa options may change. |
With finance, look beyond the headline instalment. Read the representative information and full agreement terms, including the amount repayable, payment schedule, interest or charges shown, and what the provider says happens if your circumstances change. Compare like with like: a lower-looking monthly payment may reflect a different term or total commitment. Details depend on the offer, so don’t assume one agreement matches another.
When could a finance agreement suit a sofa purchase?
Finance may be worth considering if the provider’s actual terms fit your household budget and you’re comfortable with the commitment. For example, compare an offer for a manual recliner with one for a corner sofa or suite, then weigh the full repayment obligation against your priorities. Choosing a sofa doesn’t guarantee finance eligibility, and the provider makes the application decision.
When might paying upfront or waiting be preferable?
If your budget feels uncertain, avoiding a new payment commitment may leave more breathing room. Account for essential bills and existing credit commitments, then consider whether paying upfront would leave enough savings for other needs. Waiting is a valid choice, too. You could set a savings goal, revisit sofa options later and decide when a purchase feels manageable. There’s no need to rush into an agreement.
For anyone comparing sofas on finance bad credit NI, the useful question isn’t simply which option has the lowest instalment. Consider which route leaves your household best placed to manage today’s costs and the commitment ahead. If you consider finance, base your decision on the provider’s full terms, not an assumption about what you might be offered.
Prepare for a sofa finance application without stretching your budget
Preparation can help you decide whether to apply, rather than letting the appeal of a new sofa set the pace. Start with what your household can comfortably manage, then review the provider’s information with the full commitment in view. This is especially useful if you’re researching sofas on finance bad credit NI and want to keep both your credit history and budget in mind.
A practical checklist before applying
Work through these steps, and pause if the figures or terms aren’t clear:
- Set a spending limit. Review your household income and regular outgoings, including essential bills and existing credit commitments. Decide what you could afford without relying on an optimistic change in circumstances. Set this limit before choosing a sofa or considering finance.
- Review the provider’s information. Read its current eligibility details, agreement terms and payment schedule. Look at the total repayment obligation as well as the instalment amount, and make sure you understand the commitment.
- Check your details before deciding. Review your credit file for factual errors, such as information that appears inaccurate or doesn’t belong to you. If something needs correcting, use the appropriate channel, such as the relevant credit-reference agency or organisation that supplied the information. Take time to consider the application rather than submitting several on impulse.
Keep any application accurate and consistent. If you’re unsure what a question means, read the provider’s guidance rather than guessing. The lender assesses the information submitted, so take care when completing the form. Preparation doesn’t guarantee an outcome, but it can help you make a more informed choice.
Questions to answer before agreeing to payments
Approval is only one part of the decision. Before accepting an agreement, check that you can manage the repayments alongside usual costs, including essential bills and existing commitments. Consider whether the budget still works if an unexpected expense arises, rather than assuming every month will go to plan.
- Do you understand the total amount you’d repay and the payment schedule?
- Have you read what the agreement says about missed or late payments, and what could happen next?
- Would waiting, paying upfront later, or choosing a different sofa category better fit your circumstances?
If any answer gives you pause, it’s reasonable to wait and review your options. A manual recliner, corner sofa or suite can suit different needs, but your choice also has to fit your budget. Once you’ve set a comfortable spending limit, browse sofa options at Sheepbridge Sofas & Beds, then consider finance only if the provider’s terms make sense for you.
Choose your sofa and explore finance with Sheepbridge in Northern Ireland
Start with a sofa that suits your home. Sheepbridge Sofas & Beds is a family-run Newry furniture retailer, established in 2012, with a range that includes manual recliners, corner sofas, electric recliners, and fabric and leather suites. Sheepbridge facilitates finance through third-party providers, but the lender assesses each application and decides whether to offer an agreement. Choosing a sofa doesn’t guarantee finance eligibility.
Browse sofa styles before deciding how to pay
Start with the room and how you use it. Measure the available floor space, including the route through doorways and halls, and think about how many people need to sit comfortably. A corner sofa may suit a larger layout, while a manual recliner could work if you want a reclining seat. Compare fabric and leather upholstery in light of your household’s needs and preferences.
You can browse Sheepbridge’s furniture through its Newry showroom and online store. Reviewing sofa dimensions and styles before considering payment can help keep your decision grounded in what works at home, rather than letting a payment option drive the choice. For more local context, the Northern Ireland furniture shops guide discusses local furniture retailers and what to consider as you browse.
Understand the next steps and local delivery
If you’re considering sofas on finance bad credit NI, review the current finance information for the sofa you’re considering. Read the provider’s eligibility information and agreement details carefully, including the payment schedule and total repayment obligation. The lender sets the terms, carries out credit checks and makes the decision. Take time to understand the details before submitting an application or agreeing to payments.
Keep the finance decision separate from the retailer’s role in helping you choose and purchase a sofa. Sheepbridge facilitates third-party finance applications, while the provider decides whether to approve an application and sets any agreement terms. If finance doesn’t suit your budget, you can still consider paying upfront or waiting to buy. There’s no need to rush just because you’ve found a style you like.
Sheepbridge offers free delivery and installation across Northern Ireland. Once you’ve chosen a sofa that suits your room and considered how you want to pay, explore sofas at Sheepbridge at your own pace.
Take your next sofa-shopping step with confidence
Before browsing, think about how you want your living room to feel and what the sofa needs to do in everyday life. A clear idea of your preferred size, seating and style can help you focus on suitable choices rather than feeling rushed by a payment option. If you’re considering sofas on finance bad credit NI, let your budget guide the decision and take time to read any lender terms before agreeing to a commitment.
You don’t have to decide on finance just to explore sofa styles. Start by looking for a sofa that works for your home, then consider whether the available payment route feels comfortable for your circumstances. If it doesn’t, taking more time is a sensible next step, not a setback.
Sheepbridge is a family-run Newry retailer with an online store and showroom, and offers free delivery and installation across Northern Ireland. Explore sofas at Sheepbridge and find a style that suits your home. Take the next step at your own pace, with confidence in your choice.
Frequently Asked Questions
Can I get a sofa on finance with bad credit in Northern Ireland?
It may be possible, but a poor credit history doesn’t determine every lender’s decision, and approval is never guaranteed. For sofas on finance bad credit NI, the finance provider assesses each application using its current criteria and affordability checks. Sheepbridge facilitates applications, but it can’t make or override the lender’s decision. Before applying, read the provider’s eligibility information and agreement terms so you understand what you’d be committing to.
Does applying for sofa finance affect my credit score?
The effect depends on the provider’s process and the type of credit search used. Some providers distinguish an initial eligibility check from a formal application, but don’t assume the check type without reading the provider’s explanation. Look for details about whether a search may be recorded on your credit file before submitting your information.
Can I apply for sofa finance if I have a low income?
Income alone doesn’t determine the outcome; a lender may assess affordability alongside other application details. There’s no income figure that can be given here as a qualifying threshold, and approval can’t be predicted. Before considering repayments, set out your essential expenses, regular bills and existing credit commitments. Use the finance provider’s eligibility information as your guide, and consider an agreement only if the proposed payments appear manageable within your circumstances.
What happens if my sofa finance application is declined?
The lender makes the decision, and the retailer can’t guarantee or change it. Read any information the provider gives about its decision, then consider checking your credit file for factual errors and correcting them through the appropriate channel. Avoid sending repeat applications in a hurry. You could instead save towards paying upfront, reconsider your purchase plans, or wait until your household budget feels more comfortable. A decline doesn’t mean you need to make a rushed alternative choice.
Can I pay monthly for a sofa in Northern Ireland?
Monthly payments are possible through a finance agreement, subject to its terms and eligibility requirements. Sheepbridge facilitates third-party finance, while the lender decides whether to approve an application. Before accepting an offer, check the payment schedule, total amount repayable and full agreement terms. Don’t judge the commitment by the instalment alone. If the terms don’t fit your budget, consider whether paying upfront or waiting would suit you better.
Which credit score do sofa finance providers require?
There isn’t one credit score that guarantees acceptance across all finance providers. Each lender uses its own assessment criteria and may consider information beyond a score shown by a credit-reference agency. Check your credit file for accuracy, and review the lender’s eligibility information rather than relying on a score threshold found elsewhere. Correcting an error may improve the accuracy of your file, but no particular score can promise a finance decision.
Can I choose a cheaper sofa if finance is not approved?
You can reconsider your sofa choice, pay upfront if that suits your budget, or delay buying, but choosing a cheaper sofa doesn’t guarantee lender approval. Focus on comfort, room size and household needs instead of feeling pressured to reapply. Sheepbridge offers manual recliner sofas, corner sofas, and fabric or leather suites. Finance eligibility and terms may differ, so review the provider’s information for the specific purchase before deciding.